At DTW Ignite 2026, Faisal Ghazaleh, Vice President of Solutions at Rakuten Symphony, and Manish Singh, CTO Telecom Systems for Dell Technologies, spoke with Abe Nejad of The Network Media Group about the practical realities of building the intelligent RAN. This article explores the limits of Massive MIMO, the distinction between AI in the RAN and AI on the RAN, why legacy KPIs like churn rate and ARPU are hiding the true health of the business, and why closing the gap to a truly intelligent RAN represents a go-to-market challenge that can be solved with a business-led approach.
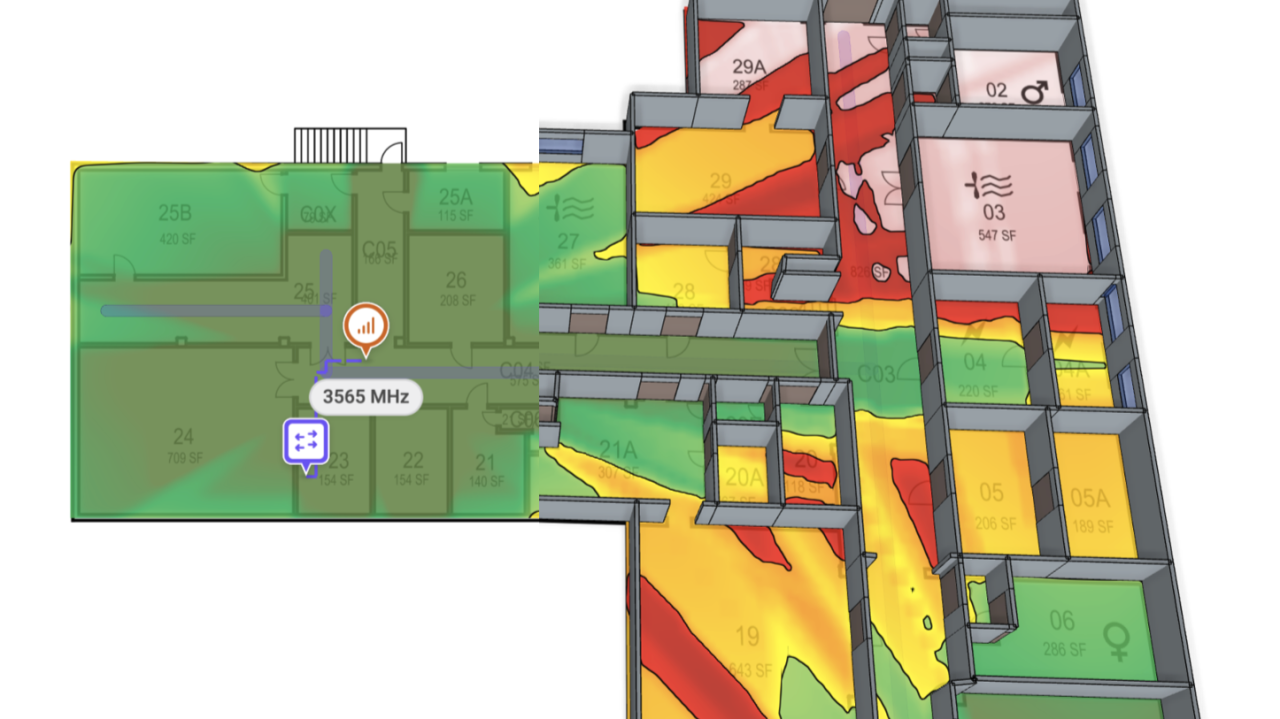
Spectrum has long been one of telecom’s most limited, expensive resources. Given the cost and challenges associated with acquiring spectrum, telcos are constantly trying to innovate to maximize its efficiency.
It is a constantly moving target.
When Massive MIMO was introduced as a key component of 5G mobile networks, it made an outsized impact on the spectrum scarcity issue, producing 2-4x increased capacity. Today, this capability has achieved upwards of 80% of active 5G RAN deployments within high-capacity, dense urban hotspots.
Spectral efficiency opportunities also extend beyond hardware. Extracting additional value represents a significant play for AI. Specifically, AI in the RAN and AI on the RAN:
- AI in the RAN addresses spectral efficiency directly, spanning the radio access stack from layer one and layer two scheduling across channel estimation, link adaptation and scheduling. It also extends across the full network lifecycle, including planning, install, commissioning, operations, troubleshooting and optimization.
- AI on the RAN is a more recent development, centered on the so-called “AI grid” concept of distributed AI infrastructure built specifically for inference. It is introducing a new conversation: whether inference should run on the cloud, core or edge, the latter of which represents priceless real estate for telcos given proximity to users.
AI on the RAN is expected to appear at the standards level in 6G networks with “low hanging fruit” use cases ready to make quick impacts.
It is understood that AI in this high-value location will not be able to operate in a vacuum. Certain decisions cannot be made without specific inputs, requiring macro decisions to occur upstream in the network. The result is edge and macro AI working collaboratively, reducing back-and-forth data transportation and traffic, and improving reaction times.
This is new territory for the network, opening the door to more sensitive, mission-critical use cases.
A business-led approach to building the intelligent RAN
The intelligent RAN’s potential is clear. So how can telcos close the gaps to more quickly build toward it?
One answer recognizes the more comprehensive approach of evaluating leadership, culture and technology together. As telecom has moved through the “G” cycles, it is already talking about 6G before 5G’s benefits are fully realized.
This is one of the drawbacks of an engineering-led approach. Think about how quickly the conversation has moved from models and chatbots to Retrieval-Augmented Generation (RAG) to agents in a matter of months with no clear picture of what the next six to twelve months brings.
As AI’s business viability is studied and measured, choices should be reassessed based on commercial outputs rather than technical ones. A promising development is 6G’s stated purpose to close the monetization gap left by 5G, which was an excellent technical solution not properly monetized for most adopters.
This time, business-driven decision making needs to take the helm with engineering serving in a supporting role.
Measuring AI RAN success
AI is not going anywhere. Its value must be planned for from the earliest stage of any blueprint instead of being bolted on later.
An outstanding, critical question is how to measure AI RAN success. Looking at the wrong numbers risks selling this transformational technology short or limiting its impact.
In an industry where stakeholders “become what they measure,” metrics like churn rate have deflected attention from underlying issues. A CSP that loses 1,000 high-ARPU, high-value customers and gains 1,000 low-value customers may have a flat churn rate on paper, but the actual subscriber mix has degraded significantly.
As discussed in the previous issue of Zero-Touch, ARPU also introduces a critical blind spot as it is completely agnostic to the margin. Yes, a CSP may be successfully attracting the highest ARPU customers but if it is at the expense of excessive acquisition and retention spend, the margins disintegrate.
KPIs that lack substance and don’t tell the true story of the business are merely red herrings.
In the AI era, where data is more plentiful and accessible, proposed replacement KPIs stand to recalibrate how telcos measure success. In particular, subscriber lifetime value (LTV), which calculates the total expected revenue or profit a business earns from a single subscriber over their entire relationship compared against real acquisition cost provides a significantly more accurate read on whether an operator’s business is on the right track.
Additionally, the concept of AI EBITDA is being presented as a way to measure whether AI is actually contributing to earnings versus metrics like token consumption, which don’t actually help telcos understand value outcomes. AI EBITDA essentially forces organizations to understand if AI investments are contributing to the business’ bottom line, or else they are not fulfilling their purpose.
It is important to have these conversations now rather than discover years into major investments that there were blind spots all along. This is especially true given that AI’s vast potential risks it being applied across domains where returns may never materialize.
Governance will bring much-needed guidance
New governance strategies will play a major role here. Specifically, a two-by-two framework that looks at expected spend against data readiness, which any business can use to get insightful answers before deployments even happen. It could apply as easily to the RAN as it does the core network or broader operations.
For instance, Dell has used the framework across R&D, product development, sales and marketing, support and services and supply chain to measure the true business impact of AI investments meant to support each.
As the market for individual subscribers saturates, AI will ultimately play a role in telco provider capabilities to pursue verticals like healthcare, oil and gas, and retail. This requires genuinely understanding these industries in a way telecom has not previously.
A maritime stakeholder doesn’t care about AI RAN itself, but it is very interested in solutions to real business problems. In logistics, the value proposition is downtime, not bytes and minutes. The closer operators get to understanding a vertical’s actual problem, the better they can serve and derive revenue from it.
The success mobile operators have built runs on the legacy “sell a SIM, collect ARPU” formula, which is optimized for a B2C world. In the AI era, it is important to recognize enterprises don’t run on the same formula and that winning B2B and vertical business means understanding the industry, which use cases are the most viable, where the necessary data lives, and what value looks like to each individual customer.
The RAN's technical capability, how AI is layered on top of it, the way it’s measured and the governance that guides investment will serve as the core foundation for telecom’s next growth phase.